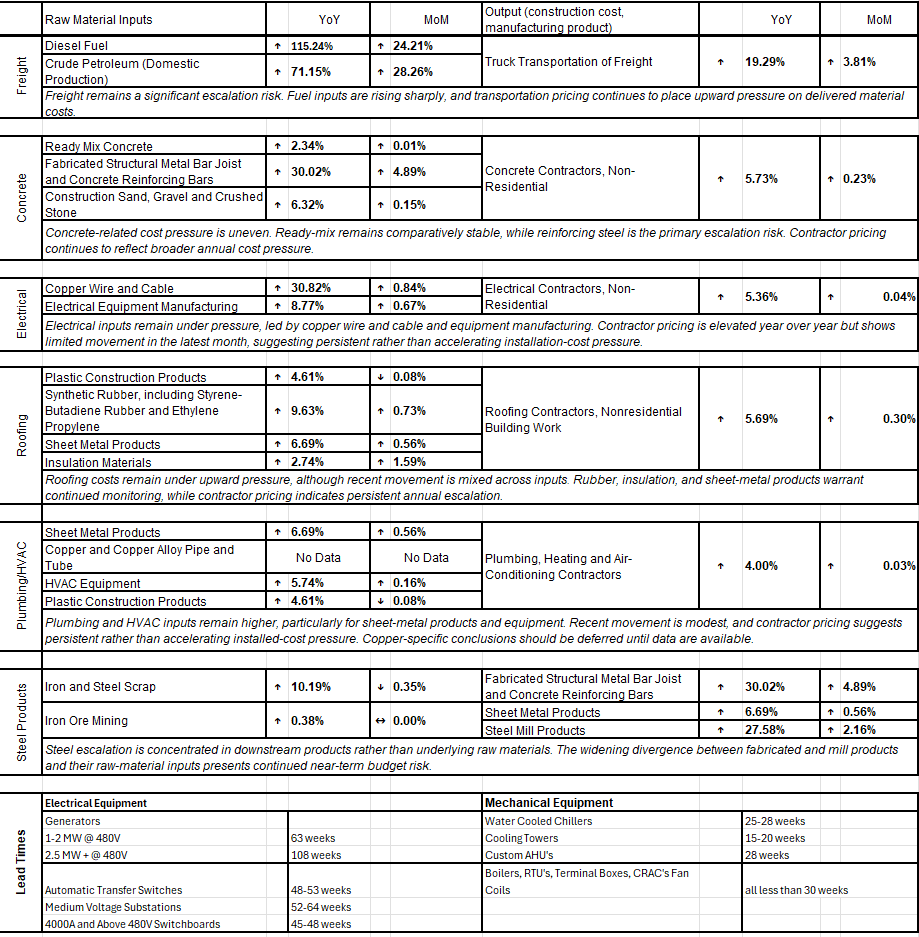
Construction cost pressure remains broad but uneven. Freight and downstream steel products are creating the strongest near-term pressure, while contractor pricing shows persistent annual escalation with limited movement in the latest month. Electrical and roofing inputs remain elevated but mixed. Current Lead time information for major Electrical and Mechanical Equipment is shown below. For detailed information and longer-term trends please see the graphs and charts above. There are three different views for materials and commodities and please continue to note the labor market information on the 4th tab. Use the arrows at the bottom of the charts to switch between views and use the drop-down menu to navigate between products and commodities.
Other notes:
• Construction inflation remains uneven. Freight and downstream steel products show the strongest current momentum, while electrical and roofing inputs remain elevated but more mixed.
• Installed construction costs remain elevated even where selected raw-material pressures have moderated. Labor, overhead, equipment pricing, risk allocation, and demand may continue to influence contractor pricing.
• Labor availability remains a regional risk where multiple large healthcare, data-center, semiconductor, infrastructure, and advanced-manufacturing projects overlap. Longer-duration projects may require labor-escalation allowances.
• Construction wage growth has moderated from its recent peak but remains a potential source of escalation on labor-intensive, multi-year projects. Refer to the labor view for the current trend and period-specific detail.
• Overall, downstream products and contractor pricing remain the primary budget concern even where selected commodity markets are stabilizing. Extended equipment lead times and category-specific supply constraints continue to warrant escalation planning.

